TPT WEEKLY
US rate declines narrow while larger OOCL shipments can seek spot reductions
2026 W43 · October 19–25 TPT WEEKLY · Nick Market information as of October 25, 2026, 23:59 China Standard Time (UTC+8); OOCL rates and request conditions added on October 26
US ocean rates kept falling this week, but the moves were small. On October 23, the SCFI US West Coast base-port rate was just $4 below the previous week, while the East Coast rate was down $17. Both weekly declines were less than 0.2%.
Scroll across to compare all columns
| SCFI route | October 16 | October 23 | Week-on-week change |
|---|---|---|---|
| US West Coast base ports | 7,525 | 7,521 | −0.05% |
| US East Coast base ports | 10,405 | 10,388 | −0.16% |
Unit: USD/FEU, or US dollars per 40-foot container. SCFI is a public spot-rate benchmark from Shanghai to base ports, including ocean freight and associated surcharges. Individual bookings still depend on origin, sailing, charges and space.
Last week's question was whether rates would fall faster once post-holiday backlogs cleared. Prices barely moved this week, while booking conditions began to ease. The more useful question now is whether a carrier will offer better terms once the shipment volume and sailing are clear.
Space is easing before prices move much
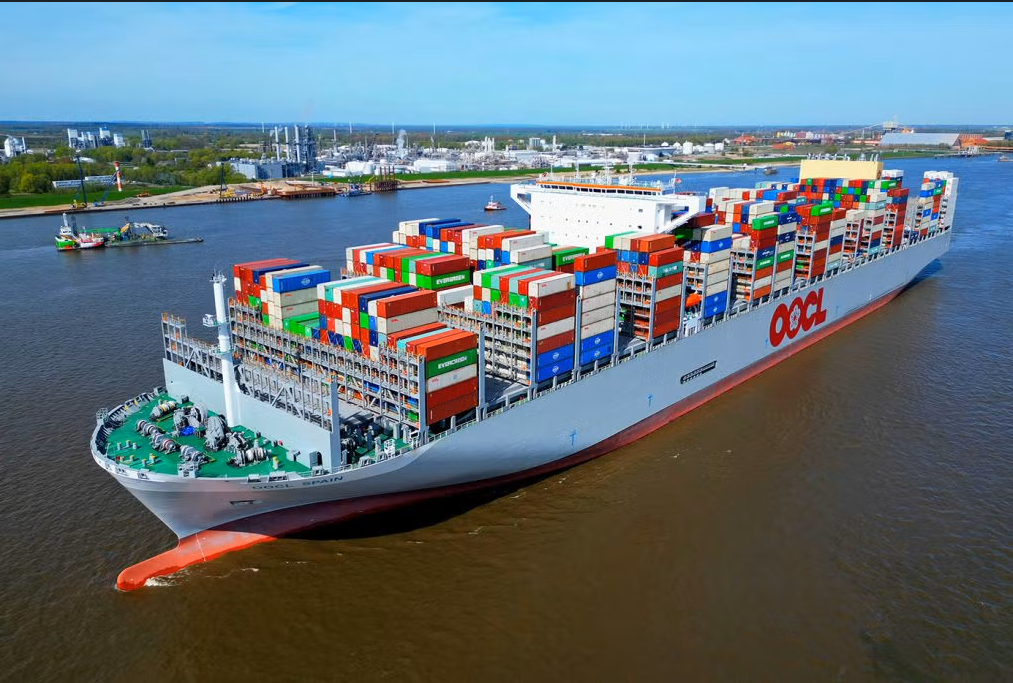
In its October 23 China–US update, Freight Right reported better booking availability on both coasts. Its October 15 update had described cargo rolled before or during the holiday taking priority over fresh bookings. At least within the bookings it observes, new cargo is starting to have more options.
That does not make every low offer bookable. The same update said some discounted products were already fully booked through October. Receiving a quote and getting an entire shipment loaded as planned remain separate questions. Sustained room across adjacent sailings would make it easier for shippers to turn those options into negotiating room.
Supply is also changing. Flexport's October 22 transpacific eastbound update described deployment staying close to full capacity and easing congestion in East China. Smoother vessel turnaround makes it easier for the same fleet to take cargo on schedule. Whether enough fresh cargo follows will influence carriers' willingness to hold prices or concede more to attract volume.
Larger OOCL shipments can request spot pricing
A small index move can still leave room to negotiate on a specific shipment. Our day-to-day service focuses on OOCL. The rates and request conditions received this week offer a reference for near-term departures.
OOCL's current FAK rates, valid through October 31, 2026, are USD 8,400/40HQ to the US West Coast and USD 11,800/40HQ to the US East Coast / Gulf, plus PNC of USD 337/CNTR per container.
For more than 12 TEU on a single sailing, a SPOT rate request can currently be submitted to OOCL. Relative to FAK, the reductions that can be sought are approximately USD 500–600/40HQ for the West Coast and USD 1,000–2,000/40HQ for the East Coast / Gulf. These are possible reductions to request; the amount granted and applicable charges remain subject to the carrier's approval.
Requests can cover sailings with ETD before November 9, 2026. The two dates serve different purposes: the current FAK is valid through October 31, while the SPOT request window extends into early November. Rates and surcharges for November departures still need confirmation for the relevant sailing.
For larger shipments with firm volumes and cargo-ready dates, a SPOT request can be considered alongside the loading plan. The saving matters, as does whether the approved terms cover the shipment's departure needs. OOCL's volume threshold applies to this request option; the same concession cannot be assumed for every shipment.
SCFI indicates market direction, while OOCL FAK and SPOT terms concern individual bookings. Origins, destinations, equipment and included charges need to match before the two sets of figures can be used to calculate a price difference.
November still depends on how the next sailings fill
How long prices hold ultimately depends on subsequent cargo volumes. On October 8, NRF and Hackett Associates forecast October arrivals of 2.25 million TEU at the major US retail import ports they cover, followed by 2 million TEU in November, a month-on-month reduction of about 11.1%. This all-origin arrival forecast gives context for a slowdown after the peak. The strength of fresh China-origin bookings in late October still needs to be judged at the loading end.
Over the next two or three weeks, the more useful signals are whether fresh bookings consistently secure space, rollovers diminish and more subsequent departures offer price concessions. Continued easing in space alongside more readily approved SPOT requests could allow price competition to extend beyond selected larger shipments. If carriers withdraw some supply and the remaining vessels fill, rate adjustment could take longer.
Near-term shipments therefore need not wait for a market-wide rate cut. When volumes, delivery deadlines and sailings are clear, the terms currently available to request can be compared. If fresh cargo then keeps building across subsequent departures and actual quoted rates rise again, the November outlook would need to be reassessed.
For market reference only. Rates, charges, space and eligible sailings remain subject to the carrier's final confirmation.
Sources
Rates: Shanghai Shipping Exchange SCFI; route-level figures reported by Economic Daily, October 23 and MoneyDJ, October 16. Weekly changes are recalculated from the two releases.
Space and capacity: Freight Right, October 23 and October 15; Flexport, October 22. Demand context: NRF / Hackett Associates, October 8.
OOCL rates and request conditions: business information added on October 26, subject to the carrier's approval for the relevant period.
Back to Insights